Bangladesh Bank on Wednesday brought five Shariah-based banks under its resolution framework, paving the way for their merger into a single entity. With this move, their boards have been dissolved, and control has been transferred to Bangladesh Bank’s newly formed Bank Resolution Department.
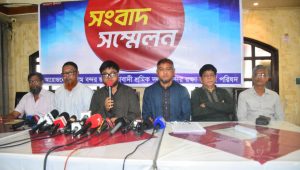
Announcing the development at a press conference, Bangladesh Bank Governor Ahsan H Mansur said none of the employees would lose their jobs and that depositors would be allowed to withdraw up to Tk 2 lakh starting this month. Larger withdrawals for high-value depositors, he added, would be announced later through a government gazette.
Bangladesh Bank also appointed administrators for the five banks on the same day. Each institution will be overseen by a five-member administrative team tasked with supervising overall operations.
The banks brought under resolution are First Security Islami Bank, Global Islami Bank, Union Bank, EXIM Bank and Social Islami Bank.
Bank resolution refers to a controlled restructuring, merger or liquidation process designed to restore financial stability without letting a weak or insolvent bank collapse. Under this law, the central bank is proceeding with the plan to merge the five institutions into a single entity.
Following the resolution move, the positions of managing directors at the affected banks have been rendered void. The central bank has formally asked the MDs of Union Bank and Social Islami Bank to resign, while the other three banks already had vacant MD positions.

Earlier in the morning, the regulator issued letters to the boards, declaring the banks non-functional under the Bank Resolution Ordinance. Company secretaries of the five banks collected the letters from the central bank’s headquarters.
The letters stated: “To protect depositors’ interests and maintain public confidence in the banking sector, your bank is declared inactive under the Bank Resolution Ordinance effective November 5. From now on, the bank will operate under this ordinance and its regulations.”
The ordinance was issued on May 9 this year.
Later in the day, Governor Mansur invited the chairmen and managing directors of two banks to the central bank for a farewell lunch, thanking them for their service since the boards were reconstituted in August last year following the previous government’s fall.
At the afternoon press briefing, the governor said, “We have dissolved the boards of the five Shariah-based banks and appointed temporary administrators. This marks the beginning of the resolution process.”
“Although administrators are being appointed, the banks will continue normal operations,” he assured. “The merger process will proceed in parallel.”
He added that the banks will remain privately operated despite temporary state ownership: “These will not become state-owned banks, and employees will not be considered government staff.”
When asked about the merger timeline, Mansur said, “It may take one year, or even two. We will take as long as necessary.”
The five banks together have 750 branches, and according to the governor, all existing employees will remain in place. Bangladesh Bank will assess whether certain branches need to be relocated.
Responding to a question on shareholder rights, Mansur said, “Given the magnitude of losses, the value of each Tk 10 share has fallen to negative Tk 350–420. Under international practice, shareholders will receive nothing as their equity has been wiped out. They will not be asked to pay more — that’s their only relief. However, bondholders will be compensated in cash or shares.”
The interim government’s Advisory Council approved the merger proposal on October 9 to combine the five private Islamic banks into a single new entity — titled United Islami Bank or Shommilito Islami Bank.
According to central bank sources, the new bank will have an authorised capital of Tk 40,000 crore and a paid-up capital of Tk 35,000 crore. Of this, the government will contribute Tk 20,000 crore — half in cash and half through sukuk bonds — while Tk 15,000 crore of institutional deposits will be converted into equity.
Initially, the new bank will be under temporary state ownership but will gradually be transferred to the private sector over about five years.
Administrators appointed
The newly appointed administrators — all from Bangladesh Bank — are set to take charge Thursday.
For Social Islami Bank, Executive Director Md Salah Uddin will serve as chief administrator, joined by Additional Director Hammada Abdul Ati, Mohammad Bazlul Karim, Md Rashedul Islam and Joint Director Rowson Akter.
At Union Bank, Director Mohammad Abul Hashem will lead a team comprising Additional Director Md Al-Mehedi Hasan, Kazi Abdul Mannan, Joint Director Md Tarikul Islam and Sagar Hossain.
Executive Director Mohammad Badiuzzaman Dider has been appointed administrator of First Security Islami Bank, assisted by Additional Director Muhammad Ansarul Kabir, Joint Director Mohammad Faisal Khan, Md Omar Faruk and Bishwajit Kumar Dey.
Global Islami Bank will be overseen by Director Md Muksuduzzaman, with Additional Director Mohammad Shahjahan, Mohammad Abdullah Al Mamun, Joint Director Md Shariful Islam and Md Kawsar Pathan.
EXIM Bank’s administrator will be Executive Director Md Shawkatul Alam, with Additional Director Sheikh Ahmed Jami, Md Raisul Islam, Md Abdul Aowal Chowdhury and Masuma Begum as team members.