


NCC Bank more than tripled its deposit growth pace during one of the most turbulent periods for Bangladesh’s banking industry, emerging with stronger capital buffers and improved asset quality as confidence faltered across parts of the sector.
The bank’s deposits rose 40 per cent to Tk30,902.5 crore between December 2023 and March 2026, compared with the growth of 12.28 per cent during the preceding three-year period from December 2020 to December 2023.
The acceleration came amid inflationary pressures, liquidity shortages and a broader erosion of confidence triggered by the deteriorating condition of several banks.
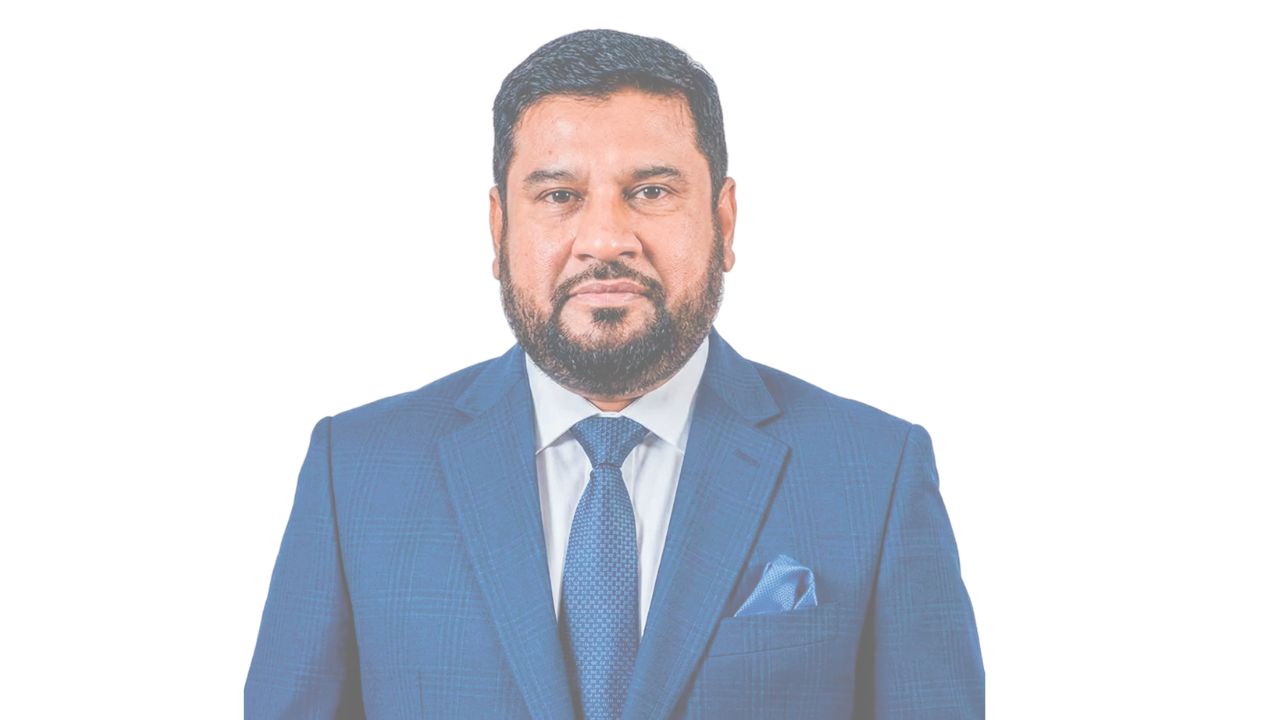
NCC Bank Managing Director and CEO M Shamsul Arefin attributed the performance to what he described as three foundations of resilience – robust governance, strategic agility and institutional strength.
“Customer confidence in NCC Bank remained unshaken despite macroeconomic headwinds, liquidity strains and sector-wide erosion of trust due to the ailing condition of some banks,” Arefin said.
The comments reflect a period in which depositors increasingly gravitated towards institutions viewed as stable and transparent, reshaping competitive dynamics across the banking sector.
While many banks struggled to preserve asset quality, NCC reduced its non-performing loan ratio to 4.29 per cent in March 2026 from 4.81 per cent in December 2023. Its capital-to-risk-weighted assets ratio strengthened to 15.54 per cent in December 2025 from 15.14 per cent a year earlier.
Shamsul Arefin said the bank’s performance was underpinned by a disciplined risk-management framework built around strict credit appraisals, cash-flow-based underwriting, early warning systems and continuous portfolio reviews.
The approach helped keep asset quality under control even as non-performing loans rose across much of the industry, he said.
Discipline over expansion
Unlike lenders that relied heavily on a narrow range of borrowers or sectors, NCC pursued a diversified portfolio strategy spanning SME, retail, agriculture and corporate banking.
The balanced exposure reduced concentration risks and prevented excessive dependence on any single segment during a period of economic uncertainty, according to Shamsul Arefin.

He said the bank’s strengthening was the result of “carefully calibrated, synchronized long-term initiatives rather than short-term fixes”.
Strong governance and disciplined oversight formed the cornerstone of that strategy. The board set the strategic direction while management operated independently within a clearly defined risk perimeter, fostering accountability, transparency and rigorous credit discipline.
NCC also tightened lending standards through risk-adjusted credit decisions that emphasised cash-flow analysis, sector-specific risk assessments and borrowers’ actual debt-servicing capacity before any facility was approved.
“This approach has markedly enhanced portfolio quality and mitigated potential asset strain,” Shamsul Arefin said.
The bank simultaneously reinforced its Early Warning System and recovery infrastructure, enabling troubled accounts to be identified earlier and addressed through restructuring, negotiated settlements or legal action where necessary. Dedicated recovery units helped improve collection efficiency.
Digitalisation broadens reach
Arefin said digital transformation became a major strategic upgrade, improving both customer experience and operational efficiency.
Digital platforms such as NCC ICON for corporate clients and NCC Always for retail customers expanded access to banking services while reducing friction and operating costs. The bank also rolled out e-KYC onboarding, QR-based payments and remote banking services that reduced dependence on physical branches.
The digital push was accompanied by efforts to diversify revenue streams. NCC expanded non-interest income through trade finance, card services, treasury operations and digital delivery channels, reducing reliance on conventional interest earnings. At the same time, tighter cost controls supported profitability.
The bank also balanced private-sector lending with investments in lower-risk government securities, helping preserve stable income and liquidity through the slowdown.
Building a future-ready bank
Having navigated the recent turbulence, NCC is now positioning itself for what Arefin described as a longer-term transformation into a stable, modern, inclusive and technology-driven financial institution.
The bank plans to deepen financing for SME, retail and agricultural customers while maintaining a selective approach to corporate and export-oriented lending to limit risk concentration and support sustainable earnings growth.
Deepening digital transformation remains a central objective. NCC aims to develop a fully integrated digital banking ecosystem with future investments focused on artificial intelligence-driven analytics, cybersecurity, automation and fintech integration.
Financial inclusion is another strategic priority. The bank intends to expand access to banking services for rural communities, women entrepreneurs and underserved customers through digital channels, agent banking and microfinance-oriented solutions.
Improving asset quality and lowering non-performing loans will remain equally important, with further tightening of credit underwriting, recovery systems and early warning mechanisms planned to support long-term portfolio stability.
Shamsul Arefin said the bank would also expand green finance and Islamic banking operations in line with evolving customer preferences and sustainability goals.
“Our long-term vision is to build a stable, modern, inclusive and technology-driven institution – one that sustains growth while safeguarding asset quality and customer confidence,” he said.