


A hundred million barrels. It sounds enormous, like a number picked to calm nerves. So when the G7 announced on Friday that it would release that much oil and diesel from emergency stocks, the obvious question was: will it actually work?
What has been agreed?
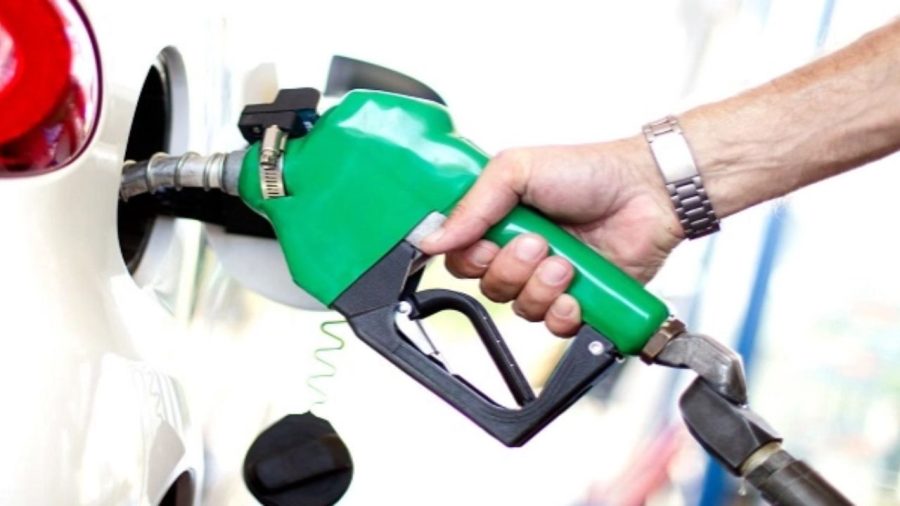
Co-ordinated through the International Energy Agency, the G7 (the US, UK, Canada, Japan, Germany, Italy and France, with the EU at the table) will release 100 million barrels, starting immediately and running over four months. It is a mix of crude and diesel, with a “substantial” diesel release front-loaded into the first 20 days. The group also pledged not to restrict energy exports among themselves.
Why diesel?
Because diesel is the fuel that moves things. Lorries and farms run on it, so when it gets scarce, the cost creeps into food. It is also harder to refine than petrol and demand is stubborn: you cannot easily ask hauliers to drive less.
Supply, meanwhile, is being squeezed from several sides. The conflict in the Middle East has restricted both crude and refined fuel. Russia, a major producer, banned its own diesel exports after Ukrainian attacks on its refineries. The result: US diesel hit a record $1.72 a litre on 22 September, and UK pump prices topped $2.64 a litre for the first time on Friday.
And where did Donald Trump’s threat come in?
This is the curious part. Trump said he backed banning US diesel exports, while his administration pressed Europe to tap its own stocks. A ban would have eased pressure on American consumers before the 3 November midterms but pushed up prices elsewhere. The US makes four to five million barrels of diesel a day and exports 1.2 to 1.5 million of them, so it matters to everyone else. More than half of the UK’s diesel is imported and 31 per cent of that comes from the US.
After the G7 deal, Trump said a ban was “never really on the table”, even though, according to Reuters, he had said in the previous two weeks that he supported one.
So is it a good thing?
Mostly, yes, for a few reasons.
First, it takes the export-ban threat off the table, at least among G7 members. Analysts warn a ban could backfire, because diesel output cannot be cut without cutting overall refinery production.
Second, markets noticed. Brent crude briefly dipped below $100 a barrel. Michael Lynch, of the Energy Policy Research Foundation, reckons reduced US exports could trim American prices by 25 to 50 cents a gallon after a few weeks.
Third, the G7 plans to co-ordinate refinery maintenance so plants are not shut at once and to encourage more diesel refining. Emmanuel Macron said the unity “should bring down prices”.
So why might it not be enough?
Start with scale. Spread across four months, 100 million barrels works out at roughly 830,000 barrels a day, some of that is crude. US diesel exports alone are higher. A French proposal discussed by EU governments, to release 50 million barrels of diesel, would equal about 17 per cent of the EU’s emergency diesel and gasoil stocks, yet only about 3 per cent of the bloc’s annual consumption.
The statement did not break down the volumes or name the countries taking part. It is also unclear how much overlaps with the record release agreed in March after the Iran war began. Energy Aspects analysts called it a “political statement” rather than a binding commitment, with a big headline number meant to persuade Trump.
Past delivery is a worry too. By the end of August, Germany, which has Europe’s largest emergency stocks, had released only around 5 million of the 19.5 million barrels it pledged in March. The US has supplied the lion’s share of that March release so far and its Strategic Petroleum Reserve is down to about 284 million barrels, the lowest since 1982.
Then there are the underlying causes. Oil climbed back to about $102 after the announcement, on fresh strikes between Saudi Arabia and the Houthis in Yemen, according to Kpler. Before the US and Israel invaded Iran, it traded around $73. Stock releases can buy time; they cannot reopen blocked export routes or repair damaged refineries.
Finally, there is the trade-off. Jim Krane, of Rice University’s Baker Institute, points out that draining stocks lowers pump prices for a while but leaves Europe with less emergency cover and the reserves will eventually need refilling. With two wars affecting refineries and exports, he says, it is hardly the ideal moment to run them down.
What should we watch?
The G7’s promised talks on extra diesel in the coming days, the EU’s oil co-ordination group meeting on 15 October, and a reported White House executive order on diesel prices that could land as early as next week.
Perhaps the fairest way to see it is as a painkiller rather than a cure: welcome, quick-acting, but unlikely to fix what is causing the pain.