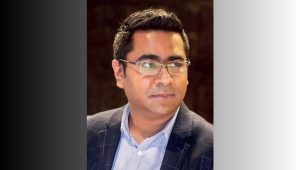


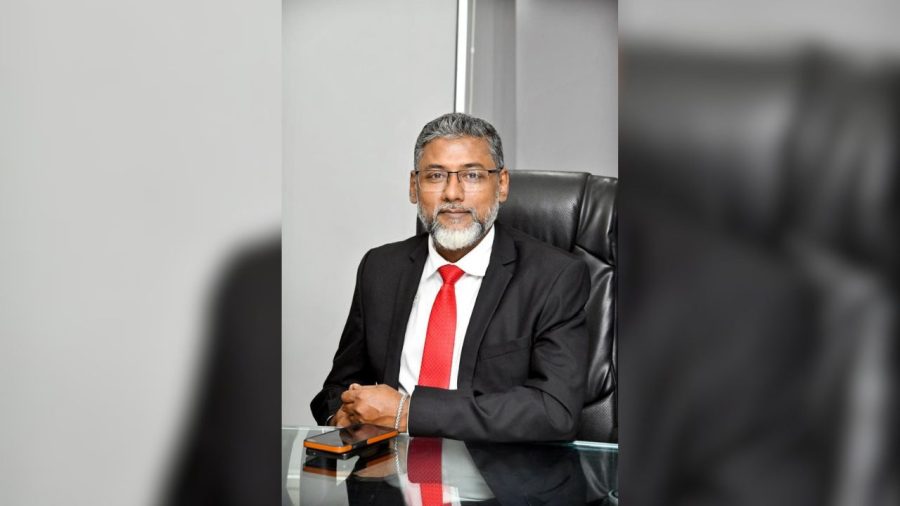

Bangladesh’s new digital banks will need more than licences and smartphone apps to make financial inclusion work, said Midland Bank PLC Head of Cards Md Abed ur Rahman.
“The bigger test will be whether the country can build shared identity, payment and data infrastructure that lets new entrants compete on equal terms,” the banker said in an interview with TIMES’ Jeffrey Dias.
With Bangladesh Bank issuing Letters of Intent to five proposed digital banks, Bangla QR expanding, One-ID being rolled out and a framework for private credit bureaus taking shape, Bangladesh is moving beyond app-based mobile money towards a broader digital finance ecosystem.
“But technology and policy directives alone will not guarantee competition or inclusion,” Rahman said.
The immediate challenge, he said, is to fix what he described as the “plumbing” of digital finance — the underlying systems that allow banks, mobile financial services providers, regulators and technology companies to work together.
He identified three priorities – coordination among institutions, consistency in rules and data access, and policy support that helps digital finance move from controlled pilots to sustainable commercial models.
On coordination, Rahman said Bangladesh needs to close the gap between policy decisions and implementation.
He pointed to India and Pakistan as examples where central banks, telecom regulators and national identity authorities have developed more integrated frameworks.
Bangladesh’s experience with Binimoy, the interoperable transaction platform that was suspended by Bangladesh Bank, shows the cost of weak coordination, he said.
Similarly, although guidelines for private credit bureaus have been introduced, limited ground-level implementation could leave digital banks and fintech companies with licences but without the data infrastructure needed to assess borrowers.
The solution is to bring ICT authorities, Bangladesh Bank, MFS providers and newly approved digital banks into the design and standard-setting process early, rather than trying to connect systems after they are built.
“True coordination” should ensure interoperability from day one, Rahman said.
Data rules present a second challenge. As Bangladesh rolls out its “Once-Only” data policy and Personal Data Protection framework, shared identity and data infrastructure will need consistent and non-discriminatory rules, he said.
A particular issue is the interaction between the Personal Data Protection Act and Bangladesh Bank’s Cloud Computing Guidelines.
New digital banks and high-volume financial institutions are likely to rely on global cloud providers such as Amazon Web Services for scalable core banking systems, making it important for regulators to clarify how data localisation, real-time local mirroring and cross-border data transfers will work.
Shared identity and data rails should operate on transparent, non-discriminatory and cost-based pricing, Rahman said.
At the same time, Bangladesh Bank and data protection authorities need to establish a clear compliance framework that allows banks to use cloud technology without breaching data sovereignty requirements.
The third issue is economics. Rahman said policy support can accelerate early adoption, but infrastructure providers and financial institutions ultimately need commercially sustainable models.
Bangladesh Bank’s push for immediate settlement and zero interchange on Bangla QR could encourage adoption, while the proposed digital banks face strict capital requirements and structured trial phases.
The next step, he said, should be carefully designed pilots that test systems before they are deployed at scale.
These could include remote electronic know-your-customer account opening and consent-based sharing of SME credit data.
Merchant economics will also matter. Regulators need to balance measures such as merchant discount rates so that acquirers have sufficient incentive to invest in payment infrastructure, Rahman said.
For digital banks, the stakes extend beyond whether customers can open accounts through their phones.
Without reliable access to identity, payments and credit data, new banks could reproduce the barriers of traditional finance despite using newer technology.
Bangladesh already has many of the components needed for a digital finance ecosystem. The question now is whether those components can be connected through common rules and infrastructure.
Rahman said the country has an opportunity to reshape its financial system, but the outcome will depend on execution.
Coordination, consistent rules and targeted policy support, Abed ur Rahman said, will determine whether the new digital infrastructure becomes a platform for wider competition and financial inclusion or simply recreates existing market barriers.