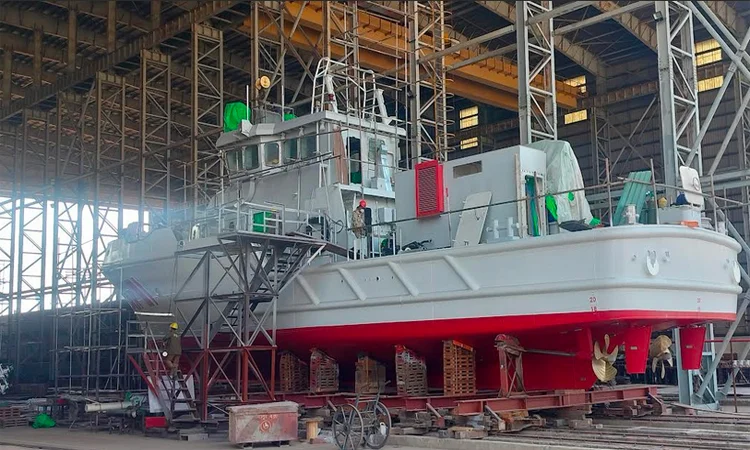

Bangladesh Bank has allowed the shipbuilding industry to reschedule loans that were classified as of 31 December 2025 for a maximum tenure of 10 years under a special facility.
The directive, which came into effect on 20 January 2026, aims to support export-oriented and local shipbuilding companies that have been genuinely affected by factors beyond their control.
Under this new arrangement, the total down payment has been fixed at 3 per cent, with the first two years treated as a grace period.
According to a circular issued by the Banking Regulation and Policy Department of the central bank, the facility will be granted based on the banker-customer relationship after assessing the merits of individual cases.

Financial mechanisms and repayment The policy stipulates that suspended interest or profit and uncharged interest related to classified loans must be transferred to a separate blocked account. The remaining principal can then be rescheduled for up to 10 years.
Regarding the down payment, 1.5 per cent must be paid at the time of application, while the remaining 1.5 per cent is due within six months of the facility becoming effective.

During the grace period, borrowers are required to pay interest on the loan on a monthly or quarterly basis. The interest held in the blocked account will be repayable without further interest in separate monthly or quarterly instalments once the grace period concludes.
Restructuring and fresh credit
Loans previously rescheduled under BRPD Circular No-12 of 2023 are also eligible for a special restructuring facility. In these instances, a maximum of two additional years may be added to the existing tenure, subject to a 2 per cent down payment (1 per cent with the application and 1 per cent within six months).
Crucially, Bangladesh Bank stated that no compromise amount will be required against rescheduled or restructured loans when companies seek fresh credit facilities to maintain their business and export operations. However, banks must maintain provisions applicable to unclassified loan standards and obtain board approval before implementing these instructions. Regular instalments for these specially rescheduled or restructured loans must also be paid on a monthly or quarterly basis; failure to do so will result in the loan being classified in line with existing rules.
Eligibility and compliance
The central bank made it clear that loans resulting from fraud and those belonging to wilful defaulters are strictly ineligible for this facility.
Before granting the rescheduling, banks must conduct special inspections to verify that the companies were genuinely affected by external factors. If losses are confirmed, banks may, at their discretion, treat the loans as eligible for qualitative classification as of 31 December 2025.
Borrowers must submit their applications with the initial cash down payment by 30 June 2026. Banks are required to dispose of these applications within 60 days of receipt.
Consequences of default
The facility may be cancelled if a borrower fails to pay the required down payment or misses six monthly or two quarterly instalments. In such cases, banks are authorised to take legal action for recovery, and the loans will not be eligible for any future rescheduling or restructuring.
Shariah-based banks have been instructed to implement similar measures for their investments in compliance with Shariah principles. This directive was issued under the powers conferred by Section 45 of the Bank Company Act, 1991, and has taken effect immediately.