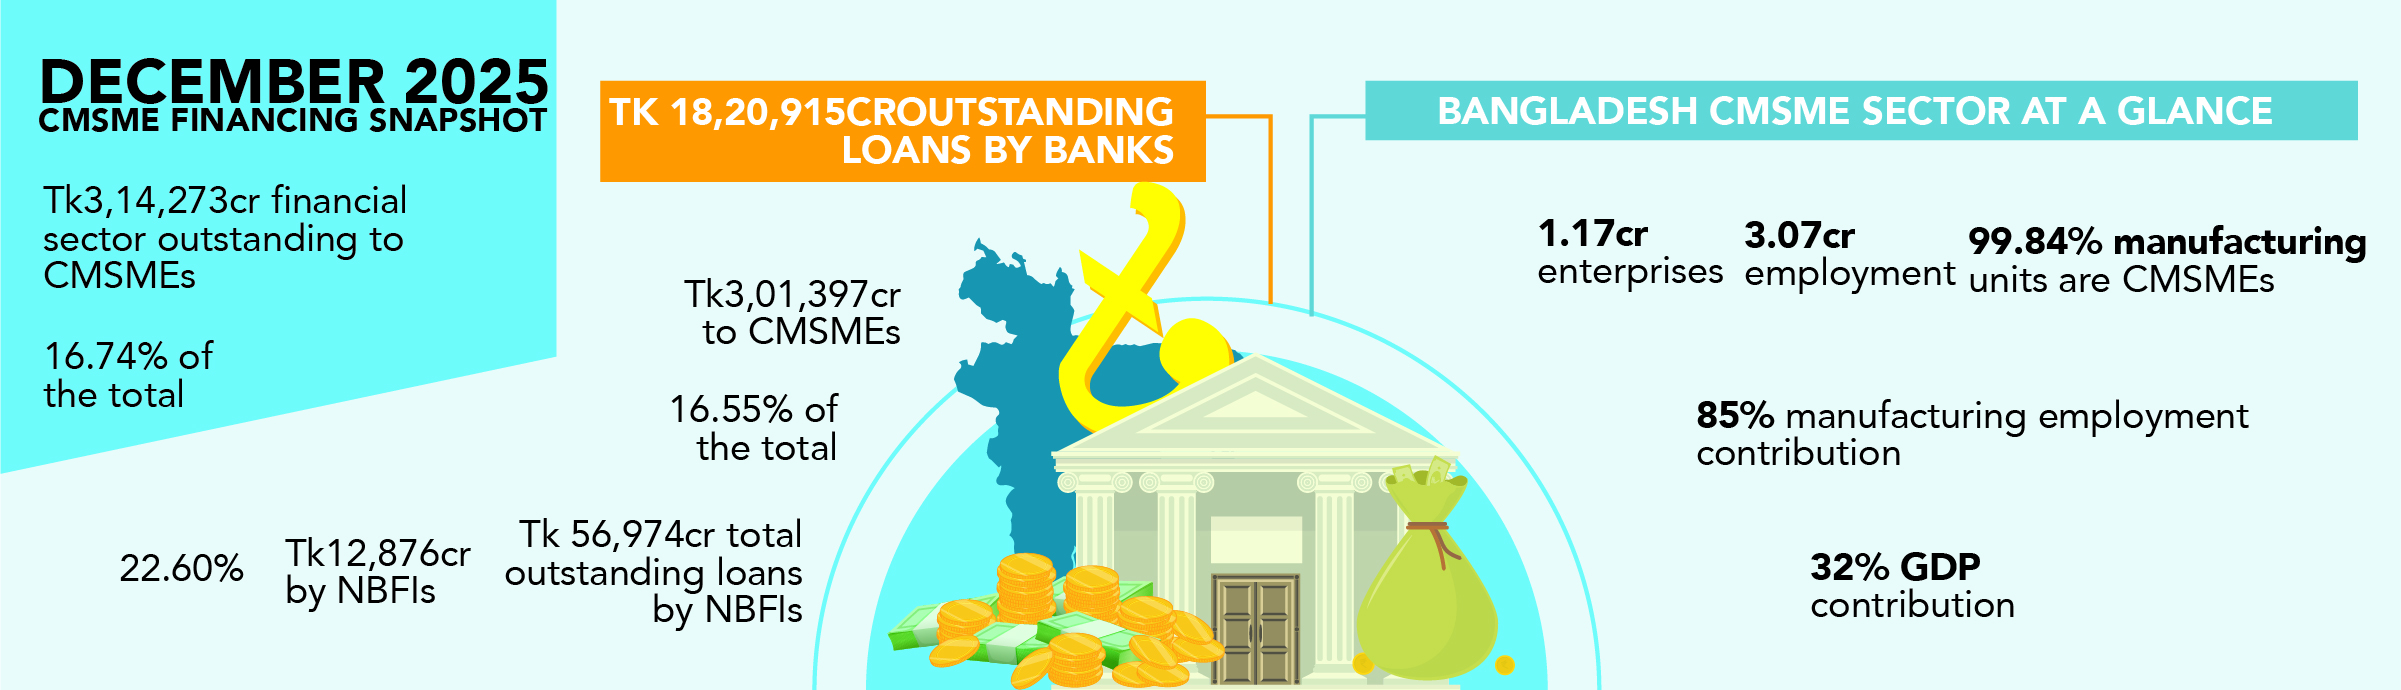
Bangladesh’s next chapter of economic growth will be shaped not only by large industries but also by the strength and resilience of its micro, small and medium enterprises (MSMEs).
As the backbone of the economy, MSMEs generate substantial employment while driving manufacturing, services, agriculture, exports and domestic commerce.
Ensuring the sector’s sustainable growth demands more than access to finance. It requires technology-driven banking, entrepreneur-friendly financial services and long-term institutional commitment.
UCB’s SME and Agricultural Banking Division serves more than 20,000 entrepreneurs across Bangladesh with a loan portfolio of approximately Tk7,259 crore.
Around 83 per cent of the portfolio is funded through the bank’s own deposits, reflecting the Bank’s strong liquidity position and sustainable financing capability.
That funding strength is underpinned by customer confidence. Over the past 18.5 months, UCB’s total deposits have grown to Tk72,300 crore, with nearly 70 per cent contributed by retail and SME customers.
From grassroots entrepreneurs to individual savers, millions have chosen UCB as their trusted financial partner, reflecting the Bank’s deep market penetration, strong customer acceptance and enduring relationships across the country.
In a banking environment where stable, diversified deposits have become increasingly valuable, the achievement represents more than balance-sheet growth; it reflects institutional credibility.

At UCB, MSME banking is one of our strategic priorities. Through our nationwide branch network and close collaboration with Bangladesh Bank and the SME Foundation, we have consistently expanded support for small businesses, particularly women entrepreneurs and enterprises in underserved regions.
A recent milestone was Bangladesh Bank’s recognition of UCB’s contribution to the Asian Development Bank-supported Supporting Post COVID-19 Small Scale Employment Creation Project.
Through the initiative, we financed more than 100 small entrepreneurs, helping generate employment and support economic recovery.
We have also introduced specialised solutions such as UCB Suchana for first-time entrepreneurs and UCB Ayma Deepti for women entrepreneurs, alongside dedicated financing programmes for agriculture and other productive sectors.
We have numerous examples of entrepreneurs who started with small-scale operations and gradually transformed them into sustainable businesses through access to finance and banking support.
Several first-time entrepreneurs and women business owners who initially approached us for modest working capital financing have since expanded production, increased employment and established stronger market positions.
Their success demonstrates how timely access to finance, combined with guidance and banking support, can transform entrepreneurial potential into sustainable economic value.
MSME portfolios offer important advantages from a risk-management perspective because they are diversified across sectors, geographies and borrower groups, reducing concentration risk.
Profitability is also attractive when supported by strong credit assessment, customer engagement and technology-enabled monitoring.
However, MSMEs should not be viewed simply through the lens of profitability. They represent long-term customer relationships that often lead to deposits, transaction banking, payroll services and other business opportunities.
Many successful corporate clients began as small businesses. A well-managed MSME portfolio can therefore be both sustainable and rewarding while creating future corporate banking opportunities.
Despite significant progress, several structural challenges remain. Many small businesses lack formal financial records, collateral or documented business histories, making conventional lending difficult.
Wider use of credit guarantee schemes, alternative credit assessment models, stronger digital financial infrastructure and greater support for business formalisation would improve access to finance.
Financial literacy programmes, entrepreneurship development initiatives and stronger market linkages are equally important.
Addressing these challenges will require coordinated efforts by regulators, banks, development partners and business associations.
Our objective is to continue expanding MSME financing in a sustainable and responsible manner. We are particularly focused on increasing support for women entrepreneurs, young entrepreneurs, agriculture-related enterprises and businesses outside major urban centres.
Alongside portfolio growth, we aim to strengthen service quality through digital solutions, data analytics and customer-centric product development.
Our goal is not only to increase financing volumes but also to contribute meaningfully to employment generation and inclusive economic growth.
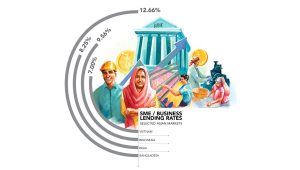
Despite economic headwinds, borrowing appetite among SMEs remains resilient as entrepreneurs continue pursuing opportunities for growth and business continuity. Demand is particularly evident in essential goods, agriculture, light manufacturing and services.
Higher production costs, inflationary pressures and market uncertainty have created repayment challenges. However, many entrepreneurs have demonstrated remarkable resilience and commitment to meeting their obligations.
Businesses with strong fundamentals, disciplined cash-flow management and market adaptability have generally maintained satisfactory repayment performance.
The outlook remains highly encouraging. MSMEs will remain central to Bangladesh’s economic transformation, employment generation and inclusive growth agenda while becoming increasingly formalised, technology-driven and integrated into domestic and international value chains.
On the financing side, digital lending, alternative credit assessment, open banking platforms, data analytics and stronger policy support will expand access while improving risk management.
Women entrepreneurs, youth-led enterprises and rural businesses will play an increasingly important role. At UCB, we remain committed to supporting that transformation as a long-term financial partner to Bangladesh’s entrepreneurs.