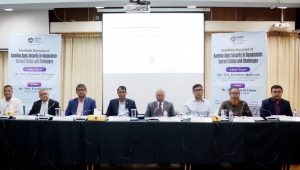


The banking system now finances 58.7 per cent of Bangladesh’s domestic government debt, up from 35 per cent in 2021, marking a sharp shift in the government’s funding sources, according to a research paper presented at the Bangladesh Institute of Bank Management’s (BIBM) Annual Banking Conference 2026.
The growing reliance on banks has come at the expense of non-bank sources, including insurers, pension funds and other investors, whose combined share has fallen from 65 per cent to 41.3 per cent over the same period.
The shift has made banks more central to government financing, raising concerns about credit availability for businesses and the need to develop alternative sources of long-term funding.
But the trend does not necessarily mean government borrowing has crowded out private investment. Weak business demand and banks’ caution over lending have also pushed lenders towards government securities.
Titled “Local Currency Bond Markets Depth and Exchange-Rate Resilience: Evidence from Bangladesh”, the paper was written by Bangladesh Bank Additional Director Mohammad Tarek and Ministry of Social Welfare Secretary Mohammad Abu Yousuf.
The 58.7 per cent share covers all domestic government debt financed through the banking system, including loans and advances from Bangladesh Bank and scheduled banks, as well as their holdings of treasury bills and bonds.
Non-bank financing includes national savings certificates and government securities held outside the banking system.
Private-sector credit growth has slowed from 13.66 per cent in FY2021-22 to 10.58 per cent in FY2022-23, 9.84 per cent in FY2023-24 and 6.49 per cent in FY2024-25.
It stood at 4.47 per cent in June 2026 before edging up to 4.75 per cent in August.
Bangladesh Bank Director and Assistant Spokesperson Shahriar Siddiqui said banks’ growing exposure to government securities did not necessarily mean public borrowing was squeezing out private investment.


Rising non-performing loans have made banks more cautious, while their boards are scrutinising lending proposals more closely. Banks are increasingly renewing existing loans rather than extending fresh credit. With businesses borrowing less, lenders are investing surplus funds in treasury bills and bonds to earn returns, he said.
Former BIBM Director General Md Akhtaruzzaman also attributed weak lending to nearly two years of political and economic uncertainty, which has discouraged businesses from making long-term investments.
Government borrowing does not automatically crowd out private credit when businesses are reluctant to borrow, he said.
The distinction matters: if banks are buying government securities because private-sector demand is weak, government borrowing is not necessarily the immediate constraint on private credit. But continued concentration of public debt in banks could increase the economy’s dependence on lenders and constrain funding available to businesses.
The government raises domestic funds through loans and advances from the banking system, treasury bills and bonds, and national savings certificates.
When investors do not buy all the securities offered at an auction, Bangladesh Bank may absorb the unsold portion through a process known as devolvement. For example, if the government offers Tk100 crore in securities but investors buy only Tk60 crore, the central bank may take up the remaining Tk40 crore.
The amount of treasury bills and bonds devolved to Bangladesh Bank rose from Tk24,536 crore in July 2021 to Tk1,22,862 crore in May 2023, before falling to Tk84,870 crore in June 2024. No treasury bills have been devolved since July 2024, but treasury bond devolvement continued, reaching Tk68,113 crore in May 2026.
The absence of treasury-bill devolvement does not mean the government has become less reliant on banks. Devolvement measures the central bank’s absorption of unsold securities, whereas the 58.7 per cent figure measures the banking system’s share of total domestic debt.
The maturity profile of borrowing also affects its cost. In 2022-23, the government sought more long-term funding when yields on 20-year government bonds reached 12–14 per cent.
Yield is the return investors expect from a bond at its prevailing market price. Higher yields raise borrowing costs over the bond’s life, while short-term bills allow the government to refinance at prevailing rates when they mature.
Although short-term borrowing offers flexibility, a narrow market and limited investor base make it harder to diversify funding across maturities.
Bangladesh’s domestic government bond market is equivalent to 9.79 per cent of gross domestic product (GDP), compared with 220.77 per cent in Japan, 69.5 per cent in Malaysia, 69.1 per cent in China, 64 per cent in India and 50.5 per cent in Thailand.
The researchers say a deeper market requires regular trading, transparent pricing and reliable benchmarks across maturities. They recommend wider participation by insurance companies, pension funds, mutual funds, financial institutions and individual investors, alongside narrower bid-ask spreads — the difference between buyers’ offers and sellers’ asking prices.
They also call for a transparent, market-based yield curve showing returns across maturities to help investors price securities and provide companies with a benchmark for issuing corporate bonds.
The paper recommends rationalising national savings certificates, which often offer higher returns than market-based government bonds. These rates increase the government’s borrowing costs and make treasury securities less competitive.
A broader bond market would give the government more domestic funding options while allowing businesses to raise long-term capital beyond bank loans, reducing pressure on the banking system, said the researchers.