
A parent paying a madrasa fee from home, a donor sending money to a mosque without carrying cash or a neighbourhood shopkeeper accepting payment through a single QR code – these are the everyday transactions Al-Arafah Islami Bank wants to bring into Bangladesh’s growing digital finance landscape.
The bank is leveraging its customer base, branch and agent banking network while expanding QR acceptance to accelerate adoption. At the same time, it is building specialised payment solutions for educational institutions, religious organisations, charitable bodies and small businesses, where cash still dominates.
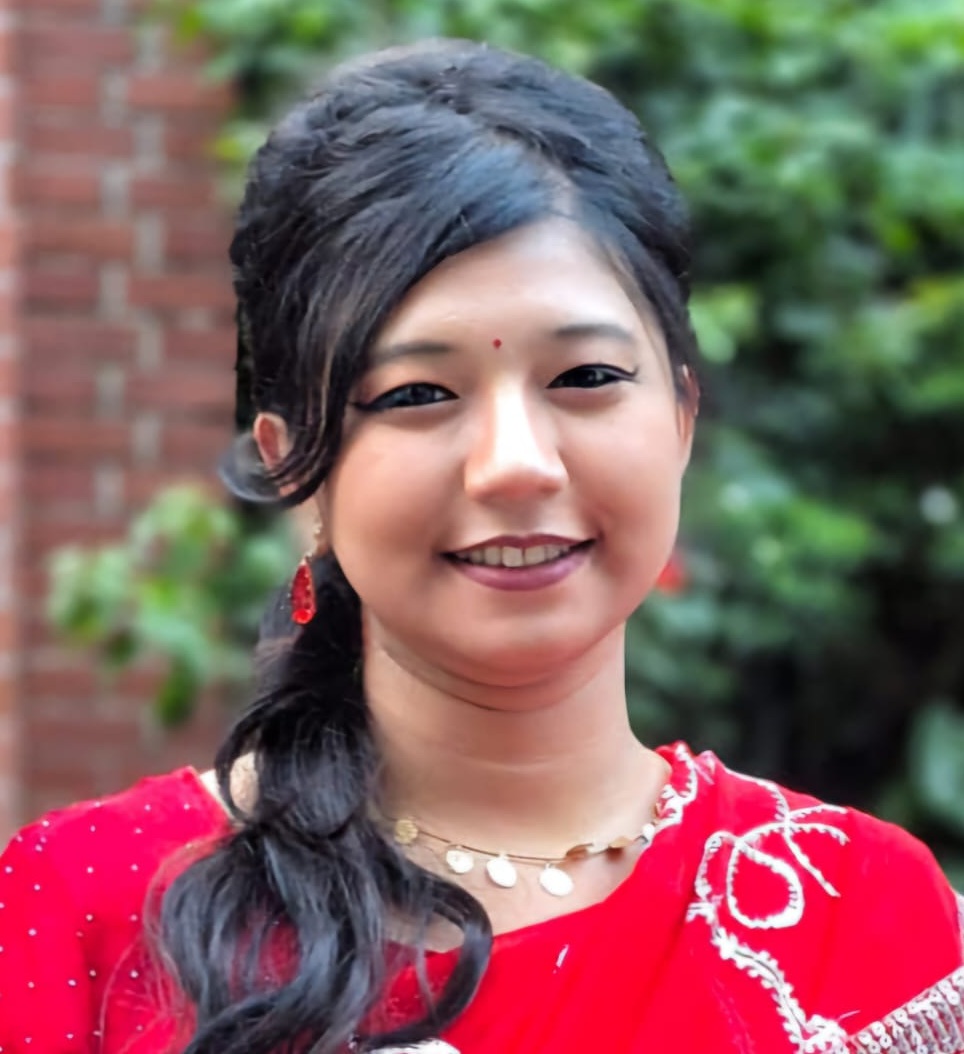
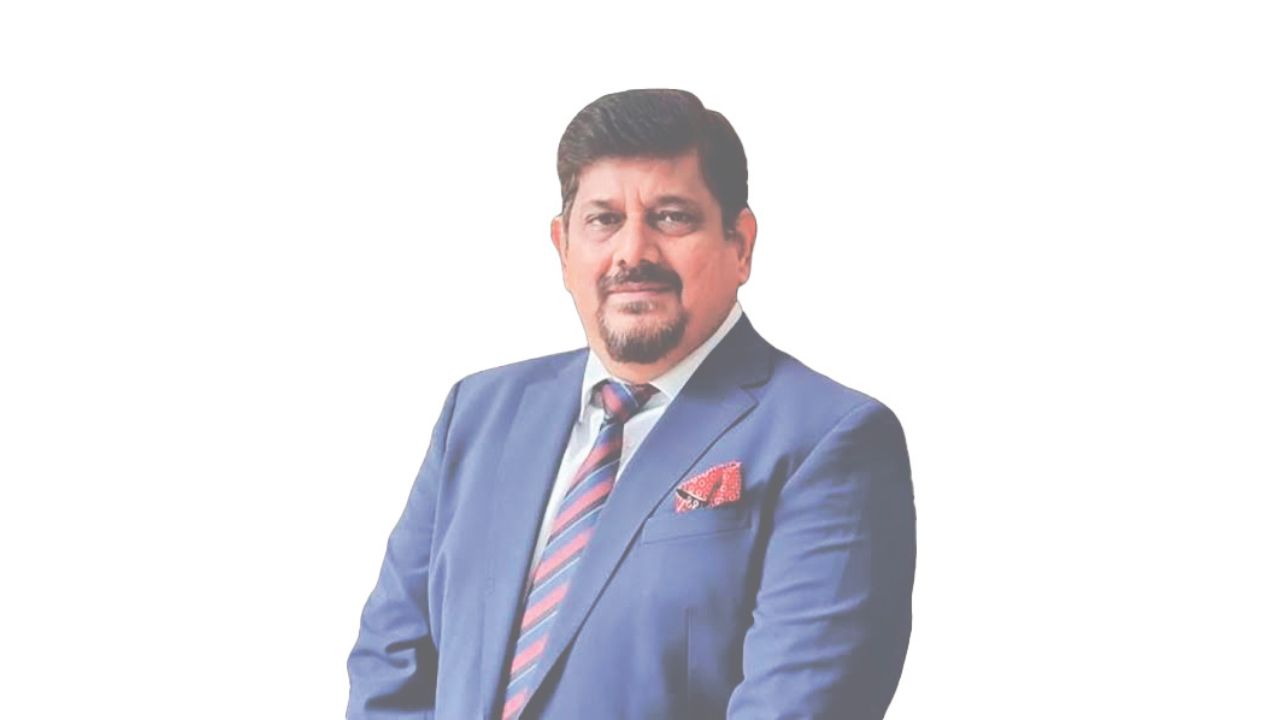
In an interview with TIMES of Bangladesh, Al-Arafah Islami Bank Managing Director Rafat Ullah Khan said Bangla QR is far more than another payment option.
“Bangla QR is not simply another payment solution. It is a major step towards building a unified digital payment ecosystem.”
He said digital payments have long suffered from fragmentation, with merchants displaying multiple QR codes and customers worrying whether their preferred banking app or mobile wallet would work. A single interoperable QR removes that complexity, making payments easier for both.
“History tells us that people adopt technology when it becomes convenient. I believe interoperability will become one of the strongest drivers of Bangladesh’s transition towards a cash-light economy.”
To encourage wider use, the bank is running a campaign offering motorcycles as prizes for Bangla QR users.
Under Bangladesh Bank’s “One Country, One QR” initiative, customers can pay through their preferred bank or digital wallet while merchants need only a single QR code.
Khan said the bank has already integrated Bangla QR into its digital ecosystem and is expanding QR acceptance across different sectors. Its branches and agent banking outlets are working with businesses to widen adoption while bringing more customers and merchants onto the interoperable network.
“Our objective has never been to introduce technology simply for the sake of innovation. We always ask one question: how can technology solve real-life problems?”
From classroom fees to digital donations
Rather than limiting QR payments to retail purchases, the bank is applying them to sectors where cash remains deeply entrenched.
Its flagship initiative, IlmNet, is a Bangla QR-based education payment platform that digitises fee collection. Every student receives an individual QR code, allowing guardians to pay tuition and other fees remotely. Payments go directly to the institution’s account, while digital records simplify reconciliation, strengthen accountability and reduce administrative work.
The bank recently signed its first institutional agreement with Bhuiangarh Daruchchunnat Islamia Kamil Madrasa.
The same model is being extended to mosques, madrasas, orphanages and charitable organisations through the Digital Dan Box, enabling donations from home and abroad while creating a transparent digital trail.
It has also introduced Digital Hadiya, allowing honorariums for imams, khatibs, hafizs and Islamic scholars to be transferred directly into their bank accounts, reducing cash handling and improving transparency.
Khan said the objective is to make digital transactions part of everyday life rather than limit them to shopping. He added that the unified QR platform could also help small businesses build financial identities.
“Every digital transaction creates a financial record. Over time, these transaction histories can strengthen a merchant’s financial profile and potentially improve access to formal financing. In many ways, today’s digital payment record may become tomorrow’s financial identity.”
Taking digital payments to the grassroots
Khan said wider adoption now depends less on technology than on changing long-established payment habits.
“Technology alone cannot achieve financial inclusion. It needs a physical touchpoint where people can ask questions, receive guidance and develop confidence.”
He said the bank’s nationwide agent banking network is evolving into local digital banking centres where merchants can register for Bangla QR, customers can learn about digital transactions and communities can become familiar with new financial technologies. Grocery shops, pharmacies, neighbourhood retailers and women entrepreneurs are gradually joining the interoperable payment network through these outlets.
The biggest challenge, he said, is behavioural.
“The real challenge is behavioural change.”
Many people still prefer cash because it is familiar, while others remain concerned about security or see little reason to change. Building confidence therefore requires consistent customer experience, awareness campaigns and reliable service delivery.
Khan said the bank continues strengthening cybersecurity through multi-factor authentication, transaction monitoring, fraud detection and continuous technology upgrades, while educating customers because many cyber incidents stem from human error such as sharing passwords, responding to fraudulent calls or scanning fake QR codes.
As a Shariah-based bank, he said innovation complements Islamic banking by reinforcing transparency, accountability and ethical financial practices through better record keeping and fewer manual processes.
Looking beyond payments, Khan believes wider Bangla QR adoption can improve business efficiency, strengthen financial records and make the economy more transparent as institutions simplify collections and small merchants build formal transaction histories.
“I would like to see a Bangladesh where digital payments become so simple that people no longer think about the technology behind them.”
Whether someone is paying school fees, buying groceries, donating to a mosque or receiving an honorarium, the experience should be equally seamless.
By combining interoperable payment solutions, Shariah-compliant digital services and its nationwide banking network, Al-Arafah Islami Bank aims to make digital finance accessible to every segment of society while contributing to Bangladesh’s transition to a smarter, more cash-light economy.